HyperSpend Targets the Back-Office Gap in Saudi Arabia’s Digital Payments Story
HyperPay’s new corporate spend platform moves beyond payment acceptance. Its relevance to Saudi operators will depend on whether real-time controls can replace fragmented expense processes.
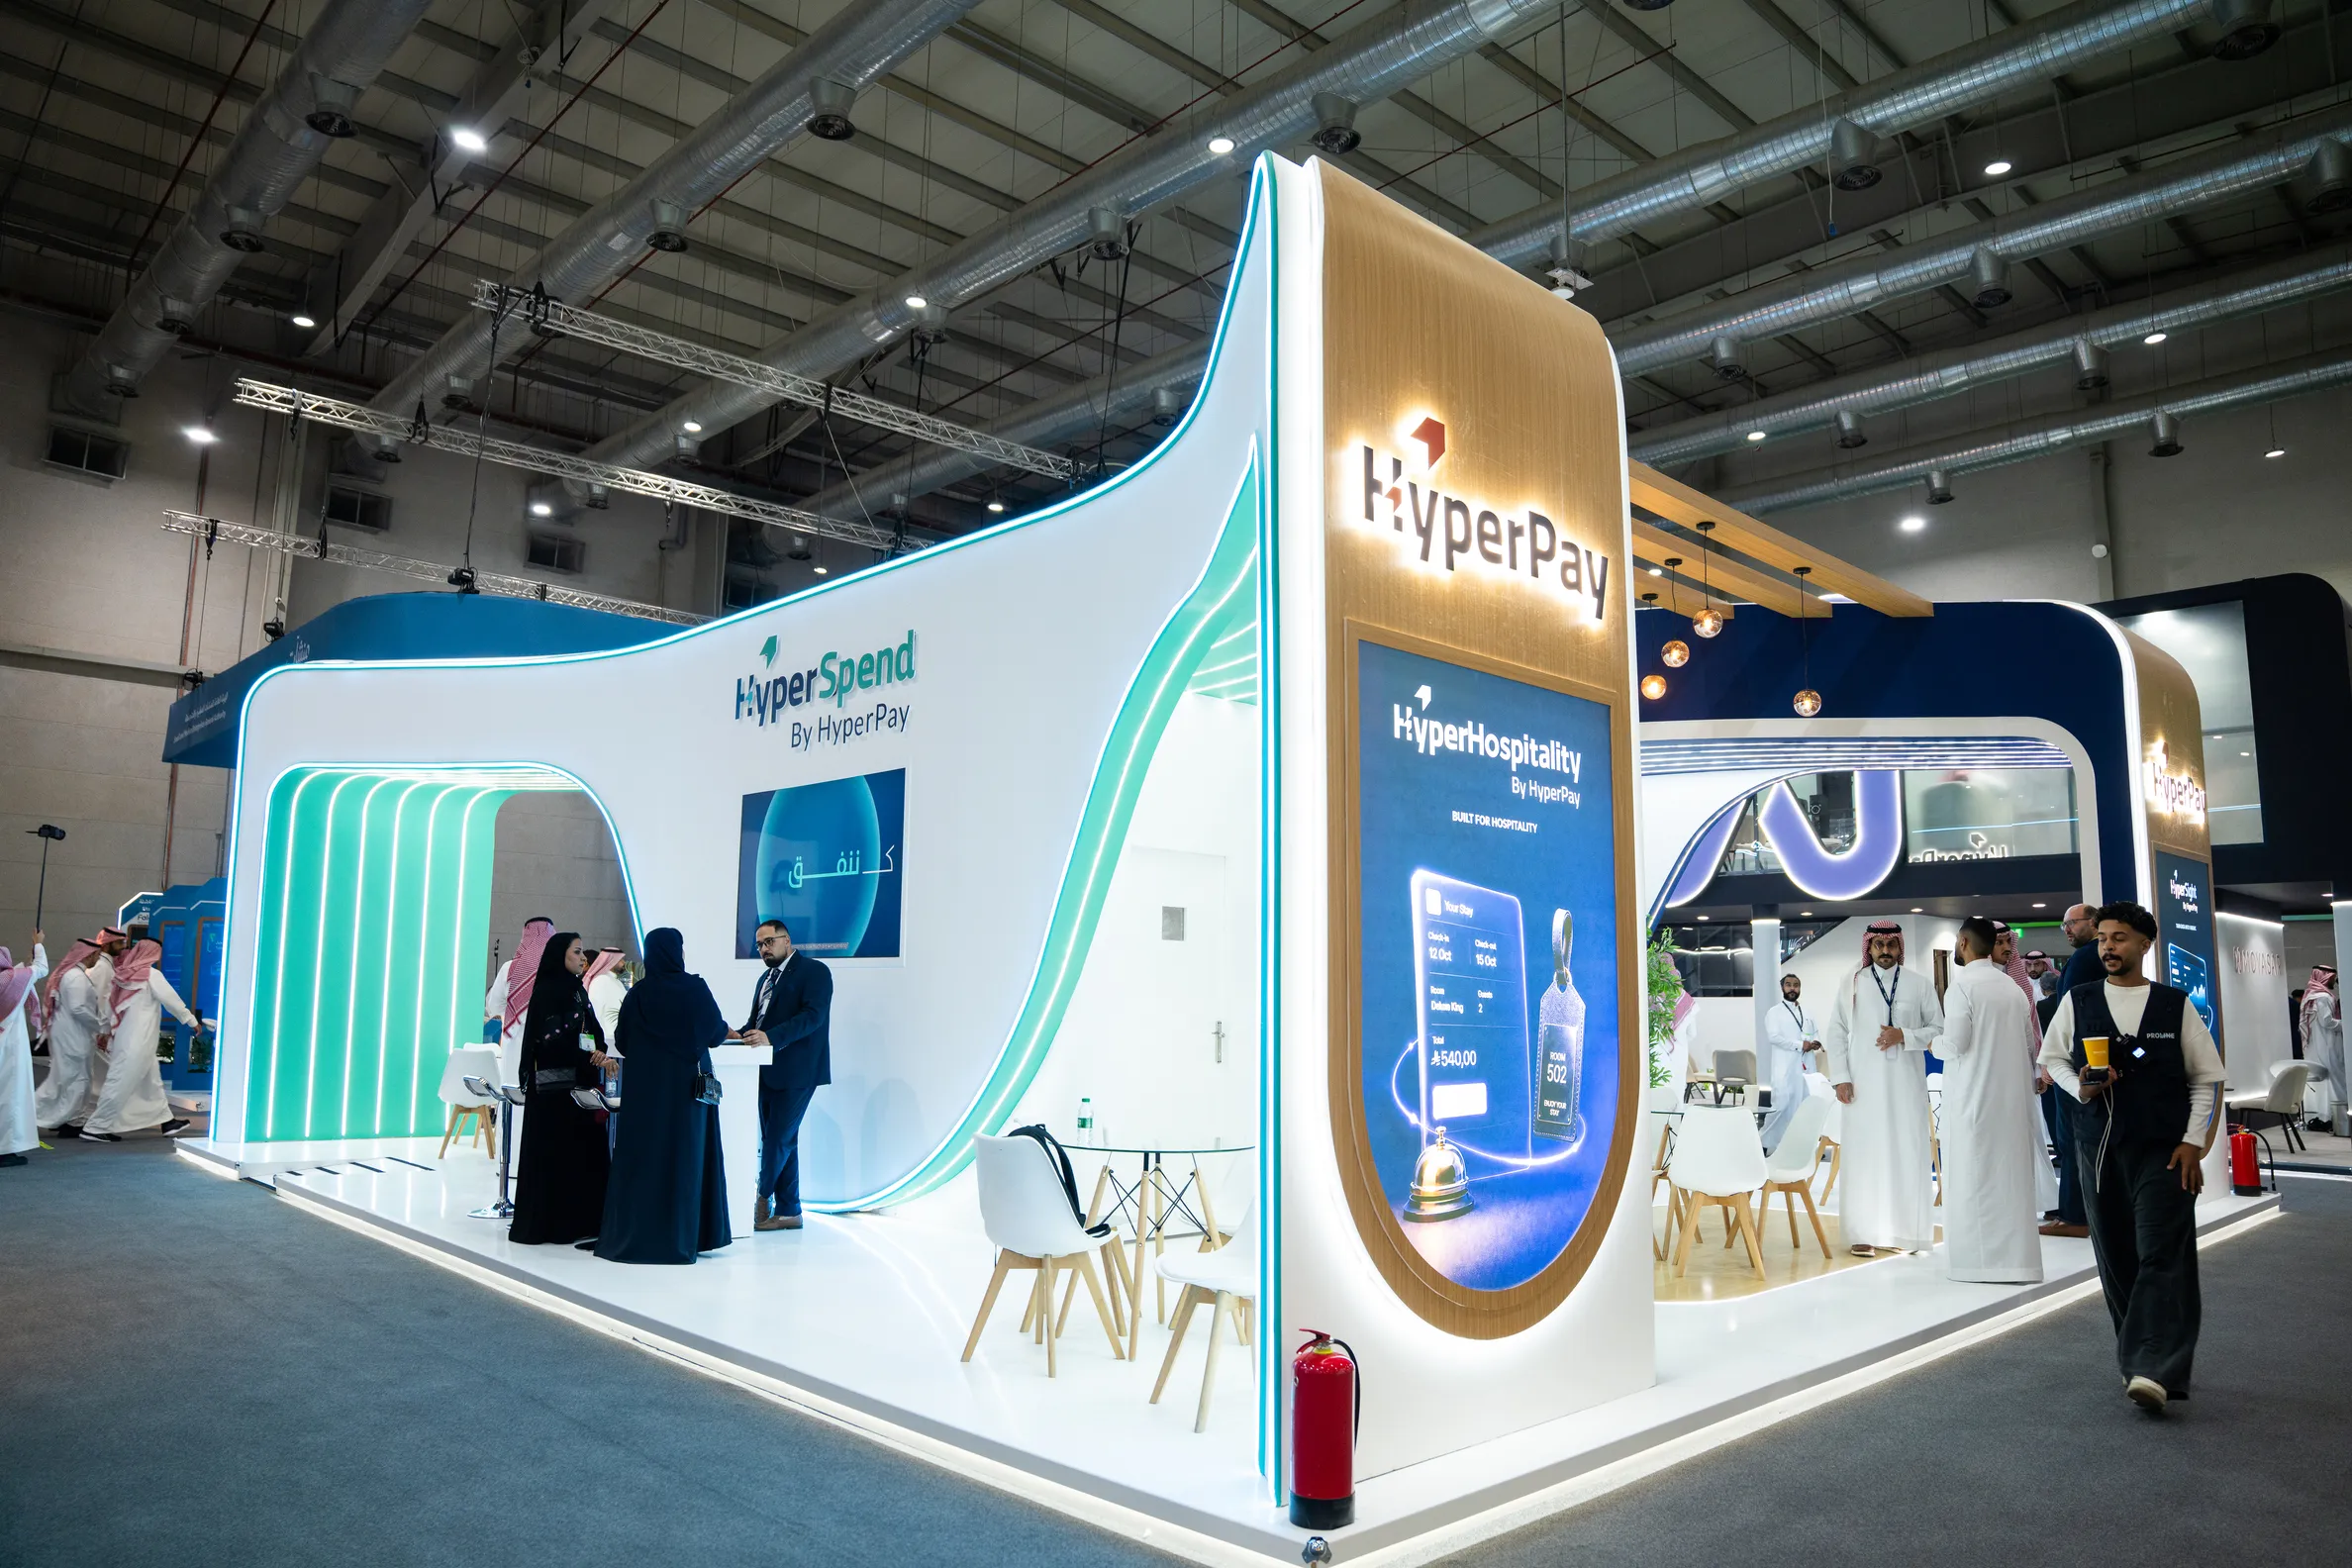
HyperPay introduced HyperSpend at Money20/20 Middle East in Riyadh on 15 September 2026, using the event’s 14–16 September run at Riyadh Exhibition & Convention Center, Malham, as the stage for a product that extends the company beyond payment acceptance and into corporate spend management.
The launch lands in a market where digital payments are already mainstream. The Saudi Central Bank said electronic payments made up 85% of total retail payments in 2025, up from 79% in 2024, with 14.6 billion electronic transactions reported by SAMA. That is an important milestone, but it also highlights where the next operational challenge sits: not only in taking payments digitally, but in controlling the money that leaves the business.
The overlooked half of digital payments
That distinction matters because many businesses have already changed how they collect revenue while leaving expense handling relatively unchanged. Customer payments may flow through modern rails, yet internal spending can still rely on shared cards, petty cash, delayed reimbursements and month-end spreadsheet reconciliation.
HyperSpend is positioned against that gap. It is a spend-management layer that HyperPay says includes virtual and physical prepaid corporate cards, employee-, department- and vendor-specific cards, pre-transaction spend caps, merchant-category restrictions, transaction rules, real-time monitoring, digital receipt capture and automated approval workflows. HyperPay’s release frames these features as part of a broader corporate spend product.
What HyperSpend controls
In practice, the appeal of a tool like this is not hard to understand. Finance teams want to decide in advance who can spend, where, how much and under what conditions. Managers want to limit the risk of overspend without turning every purchase into a manual approval chain. Operators want receipts and transaction data to arrive in a way that makes reconciliation less painful at month end.
That is where the platform’s controls become relevant. Pre-set caps and merchant-category restrictions can narrow what a card can be used for. Department- or vendor-specific cards can separate spend by function. Real-time monitoring can show transactions as they happen rather than after the fact. Receipt capture and approval workflows can make the paperwork around spending less fragmented.
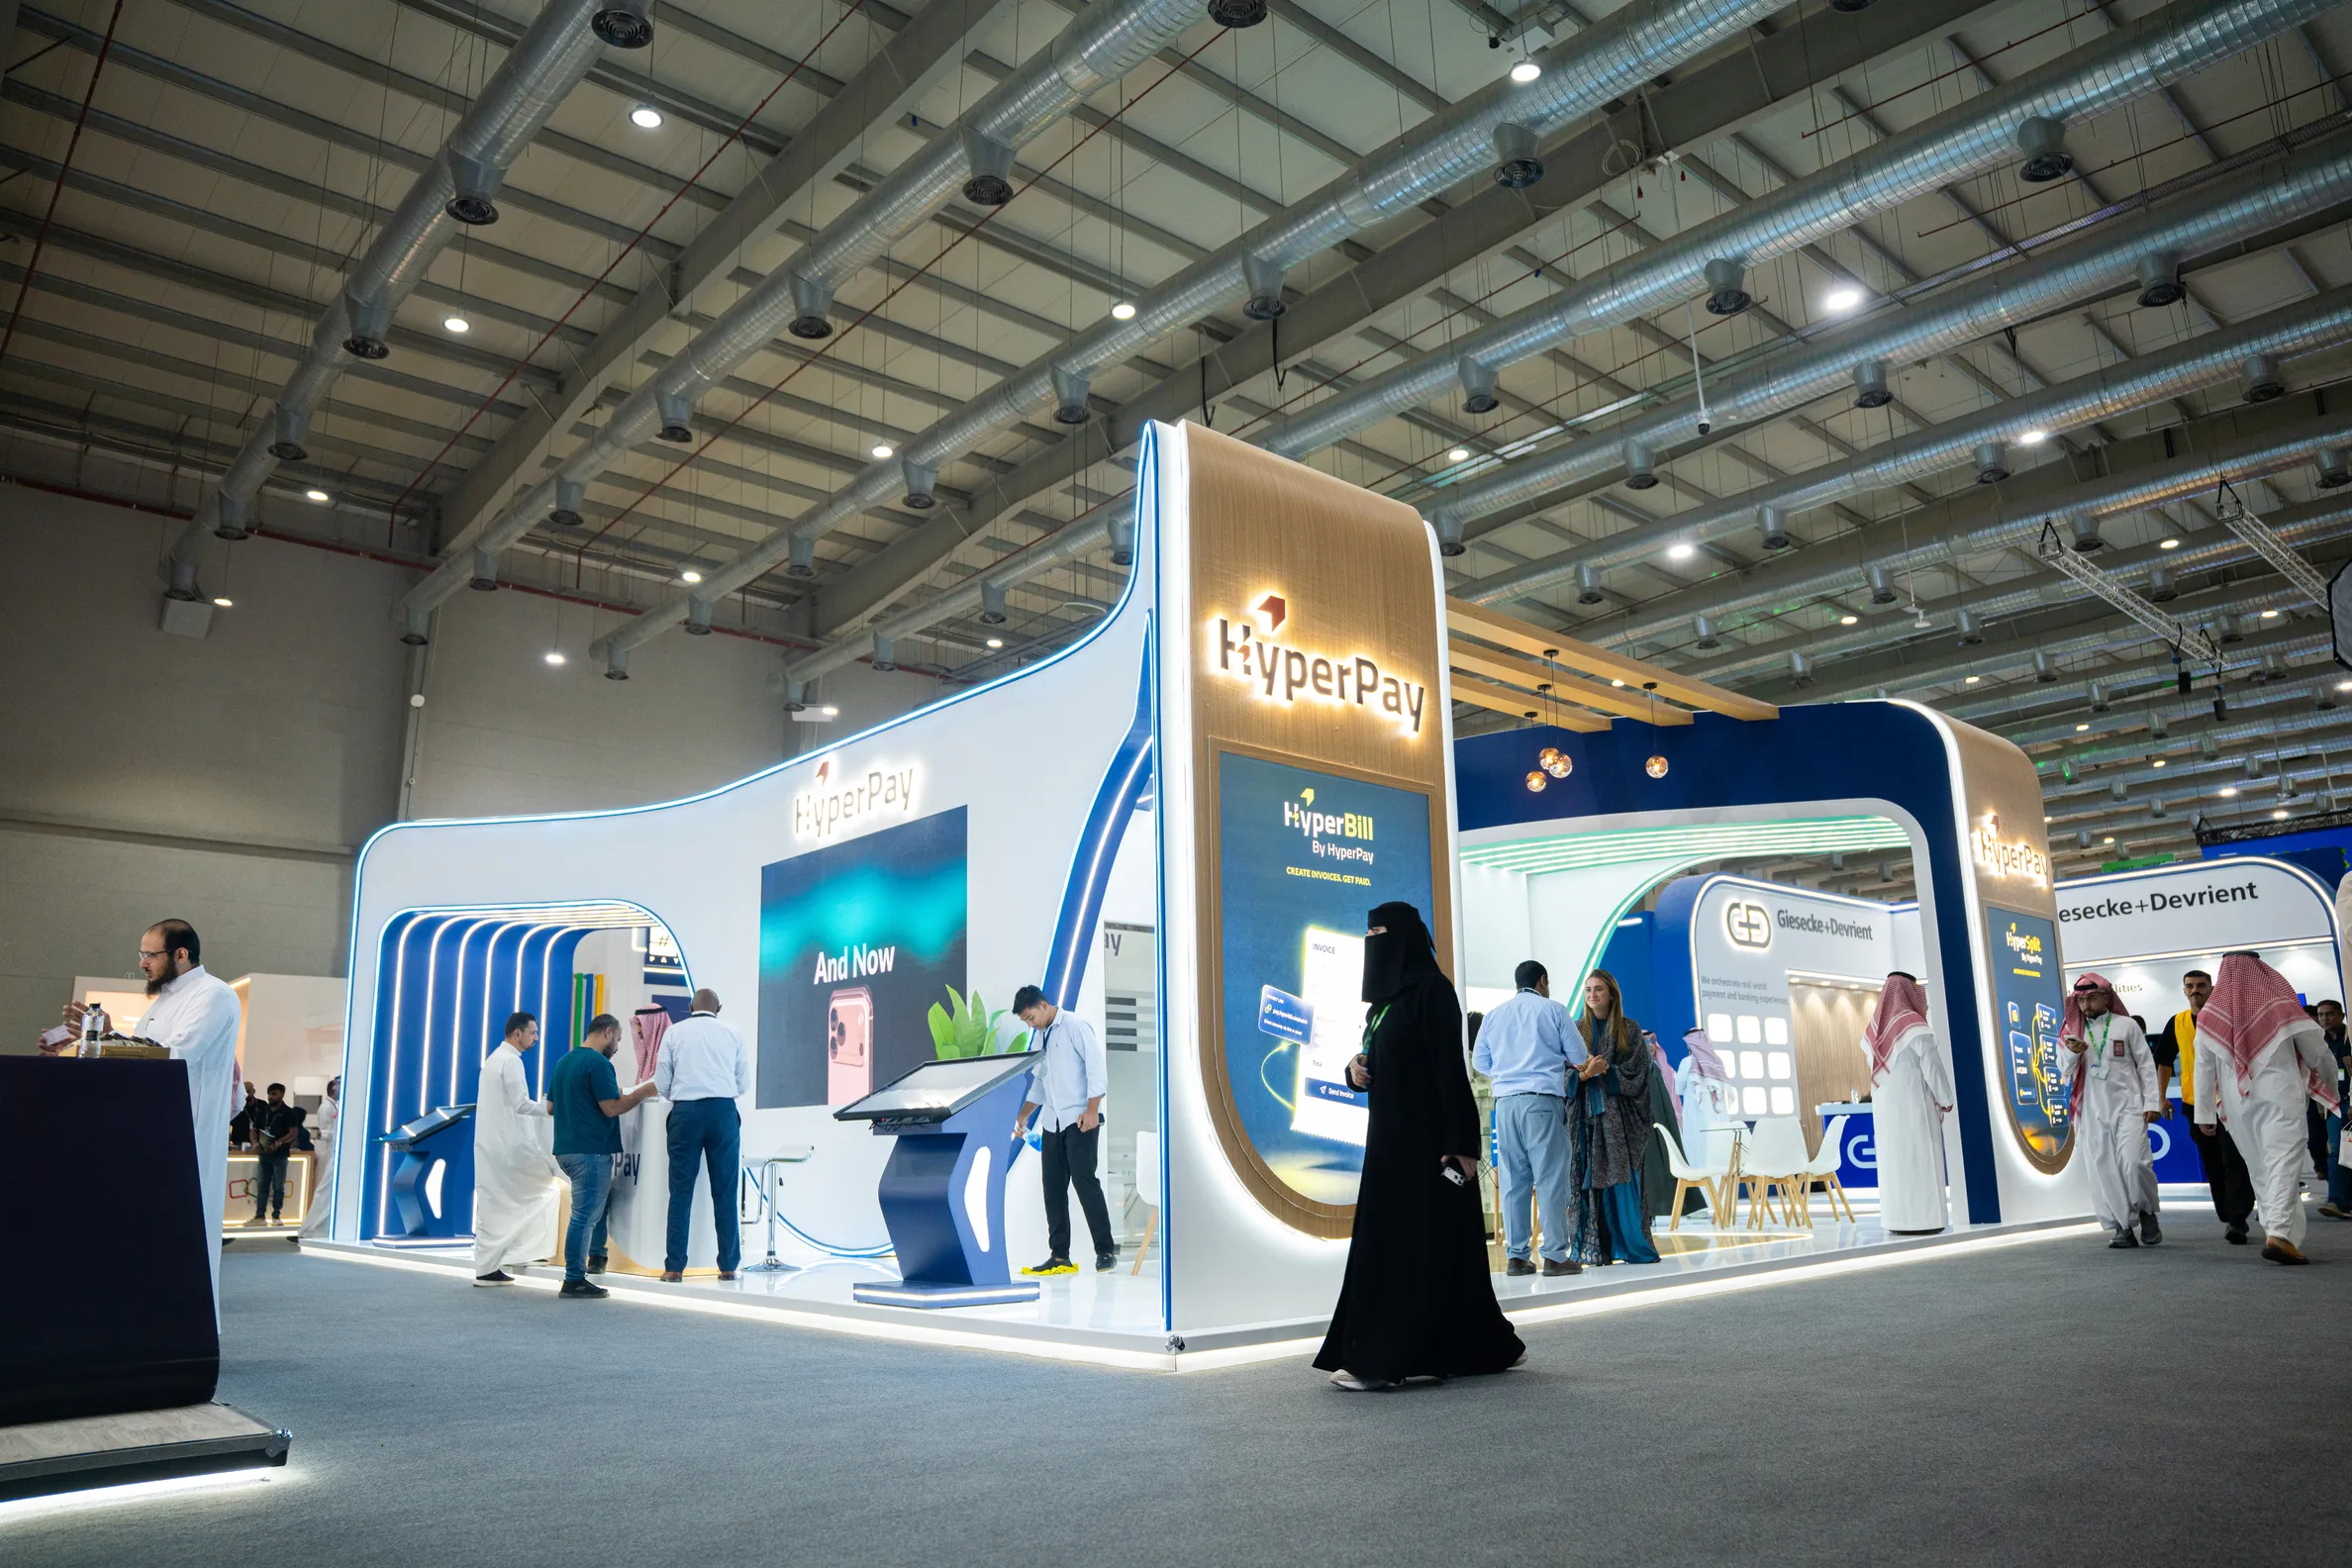
HyperPay introduced HyperSpend during Money20/20 Middle East 2026 in Riyadh.
HyperPay also says the card and payment capabilities are supported by its commercial collaboration with Mastercard, while the company says it is licensed by the Saudi Central Bank. Those claims matter because spend-management tools depend on trust, payments infrastructure and the operational reliability of the rails underneath them. The launch therefore sits at the intersection of payments, compliance and internal finance operations.
Why experience businesses should pay attention
This is where the story becomes more than a fintech announcement. Hospitality groups, food-and-beverage operators, entertainment venues and tourism businesses often work with multiple outlets, shifts, departments and vendors. They also tend to make frequent, small and time-sensitive purchases that are awkward to manage through reimbursement-heavy processes.
These sectors could find granular controls useful. A department-specific card for one outlet, a vendor-specific limit for one event, or a merchant-category restriction for a procurement type can help create more order in businesses where spending is distributed across many people and many locations.
That matters in a market where operating scale is growing. Monsha’at reported 1.7 million active commercial registrations at the end of the third quarter of 2025 and more than 8.4 million SME workers as of the end of August 2025. More businesses, more employees and more outlets all increase the cost of manual processes. Even when payments are digital, finance work can still be highly manual.
Mastercard’s SME Confidence Index for Saudi Arabia offers a similar signal, though again the figures relate to surveyed Saudi SMEs rather than all SMEs in the market. In that survey, 99% of respondents accepted digital payments and 97% said better data, analytics and insights were important to strengthening their businesses. That suggests a business audience already looking beyond acceptance toward operational visibility.
Adoption will decide the outcome
The launch itself is only the starting point. The real test is whether businesses can embed the product into daily operations without creating another disconnected finance tool.
Adoption will depend on integration with accounting systems, clarity around approvals, ease of use for employees and managers, and whether finance teams actually experience less friction. Real-time controls sound attractive, but they only matter if they reduce the burden of chasing receipts, correcting overspend and reconciling end-of-month paperwork.
“With HyperSpend, we are extending that capability to transform how they manage their own spending.” — Muhannad Ebwini, founder and CEO of HyperPay
That ambition is clear. What remains unproven is how widely businesses will use it and whether it becomes part of standard operating practice. In a payments market that has already moved quickly on acceptance, the more interesting question is whether the same pace of change will reach the back office.